The United Arab Emirates is progressively introducing mandatory electronic invoicing under a phased implementation programme. Large businesses with annual revenue of AED 50 million or more must implement the system from January 1st 2027, followed by smaller businesses from July 1st 2027 and government entities from October 1st 2027.
On October 19th 2026, the UAE Ministry of Finance announced Ministerial Decision No. 197 of 2026 [↗︎], amending certain provisions of Ministerial Decision No. 243 of 2025 on the Electronic Invoicing System. Effective from October 1st 2026, the amendments introduce several targeted measures to ease compliance and facilitate implementation.
Official legal text: Ministerial Decision No. 197 of 2026 [↗︎] — Amending Certain Provisions of Ministerial Decision No. 243 of 2025 on the Electronic Invoicing System (Arabic version).
Temporary exclusion for transactions within the same Tax Group
Business transactions between members of the same Tax Group will be treated as excluded transactions for 24 months, starting on January 1st 2027.
This temporary measure gives affected businesses additional time to adapt their invoicing processes.
Greater flexibility for electronic invoice data storage
Ministerial Decision No. 197 of 2026 removes the requirement to store electronic invoices, electronic credit notes and associated data within the UAE, allowing businesses greater flexibility in choosing where their records are stored.
However, businesses remain responsible for retaining these records for the period prescribed under the Tax Procedures Law and ensuring that they can be provided to the FTA upon request.
Removal of the system failure notification requirement
Ministerial Decision No. 197 of 2026 removes the specific obligation for issuers and recipients to notify the Federal Tax Authority (FTA) of a system failure within two business days.
Under the former Article 12 of Ministerial Decision No. 243 of 2025, both the issuer and the recipient of electronic invoices were required to report such failures to the FTA within two business days of their occurrence, in accordance with the applicable notification procedures.
Issuance window: 14 business days
The deadline for issuing and transmitting electronic invoices and electronic credit notes is extended to 14 business days, instead of 14 calendar days, from the date of the Business Transaction.
The Decision also introduces drafting adjustments concerning excluded transactions and persons excluded from the scope of the Electronic Invoicing System. These include an amendment to the definition of “Accredited Service Provider” and the introduction of definitions for “Tax Group” and “Taxable Person”.
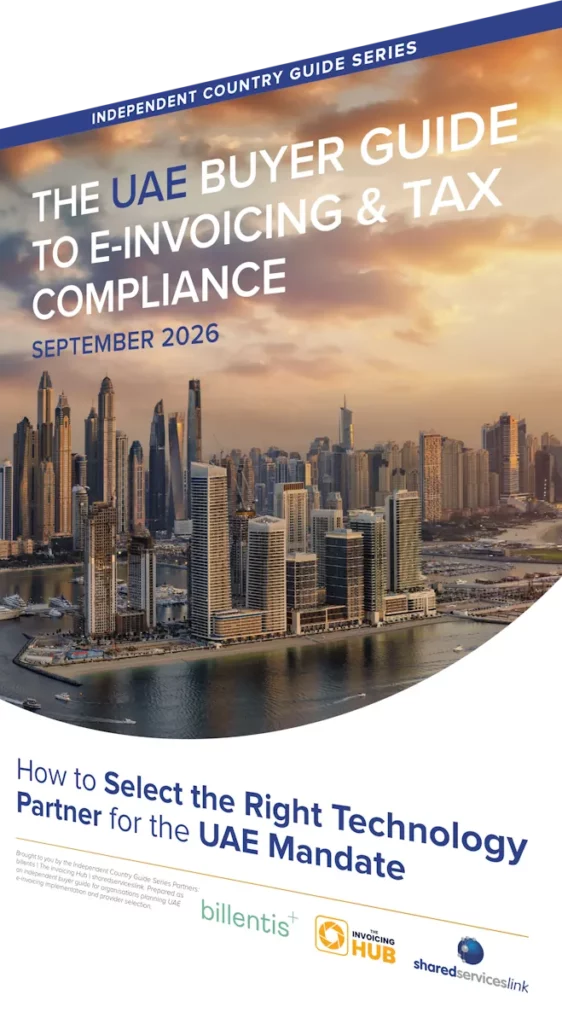
UAE Buyer Guide on E-Invoicing & Tax Compliance
We have partnered with billentis and sharedserviceslink to publish a free, neutral buyer guide for organisations preparing for UAE e-invoicing. It offers a practical overview of the regulatory and technical framework, as well as an in-depth comparison of more than 60 Accredited Service Providers.
Designed to support informed, confident provider selection, and featuring a foreword from the UAE Ministry of Finance, the guide uses objective criteria and information provided directly by providers or available publicly. Download the UAE E-Invoicing Buyer Guide