Croatia does not impose a structured B2C e-invoicing mandate, but instead requires systematic e-reporting following a Clearance model, in a process referred to as “Fiscalization” and applied to all invoices and receipts issued to final consumers.
B2C obligations already existed in Croatia to some extent, and the new regulation, also part of the Fiscalization Act 2.0 [↗︎], broadened the scope to most B2C transactions (invoices, receipts, …) and forms of payment (cash, card, …).
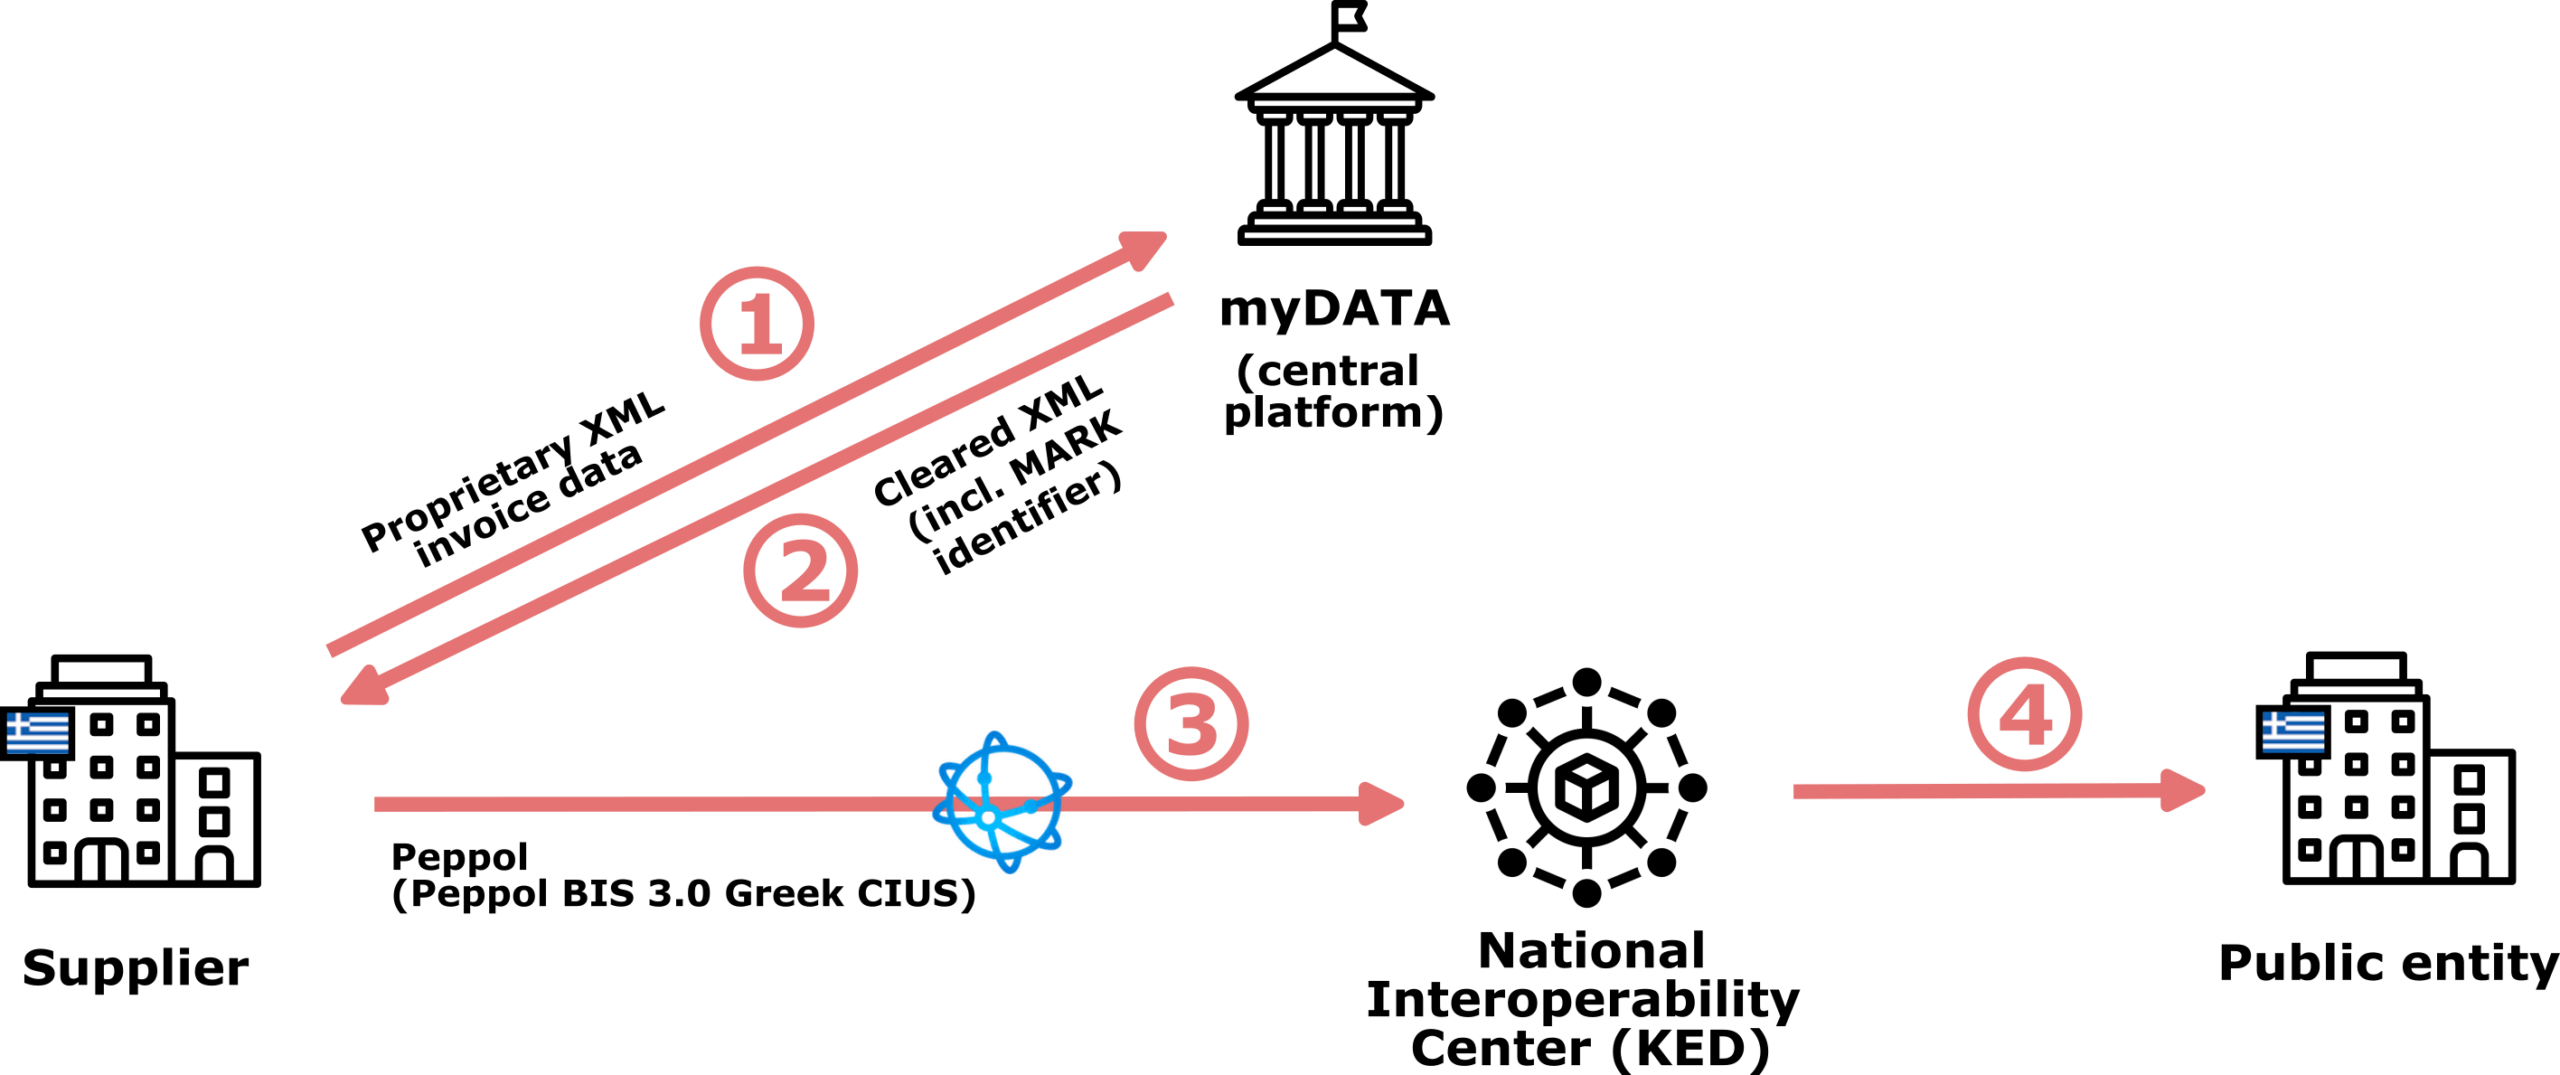
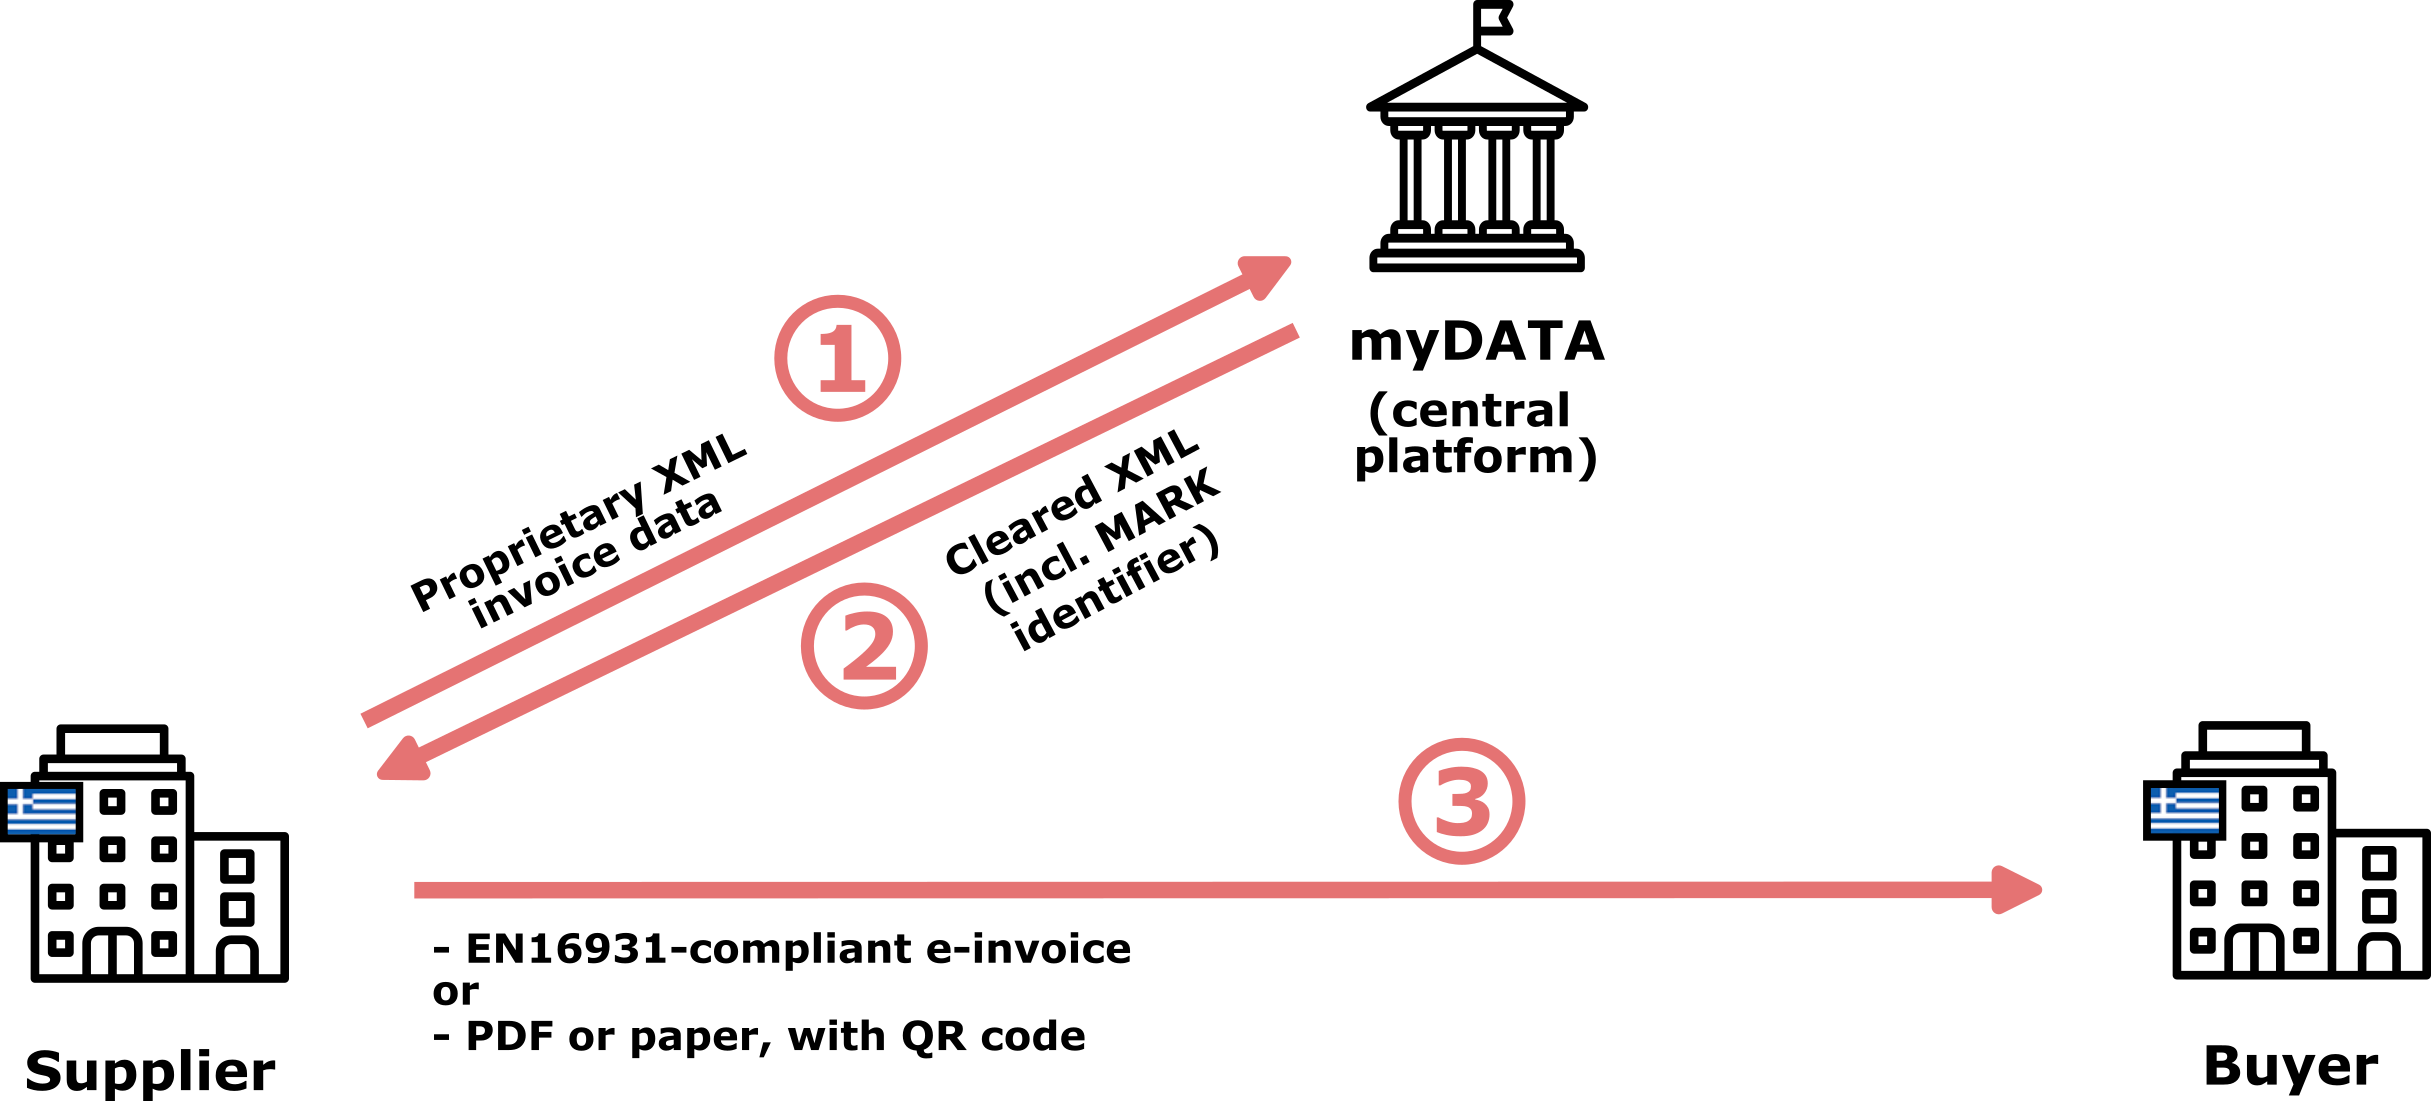
This B2C obligation requires the supplier to submit tax-related invoice data of B2C transactions to the tax authority via ePorezna [↗︎] (eTax), the tax authority portal, in a proprietary XML format for validation.
Upon success, the administration sends back to the invoice issuer a unique identifier called JIR (Jedinstveni Identifikator Racuna) confirming that the invoice has been successfully validated.
The issuer is then responsible for including this identifier in the final invoice / receipt (typically as a QR code) before delivering it to the customer, most often as a printed or PDF document, as final consumers are typically not equipped to receive electronic documents.
This requirement applies to any type of software that generates B2C invoices, including both traditional invoicing solutions and cash register systems.
Unlike the B2G and B2B mandate, which will be implemented in two phases, the B2C obligation is in full effect since January 1, 2026.
Certain B2C activities are exempt for the mandate, under Article 4 of the Fiscalization Act 2.0, such as passenger transport ticket sales, postal and financial services, or insurance.
Invoices must generally be archived for six years.