E-Invoicing in Ireland:
B2G Rules & 2028-2030 B2B Mandate
Last update: 2026, October 6
Summary
Ireland requires public administrations to be able to receive electronic invoices and will introduce mandatory B2B e-invoicing and real-time reporting in phases from November 2028. Drawing on the existing B2G approach, the B2B framework is expected to rely on the Peppol network.
B2G Transactions
Mandatory e-invoicing acceptance by public administrations
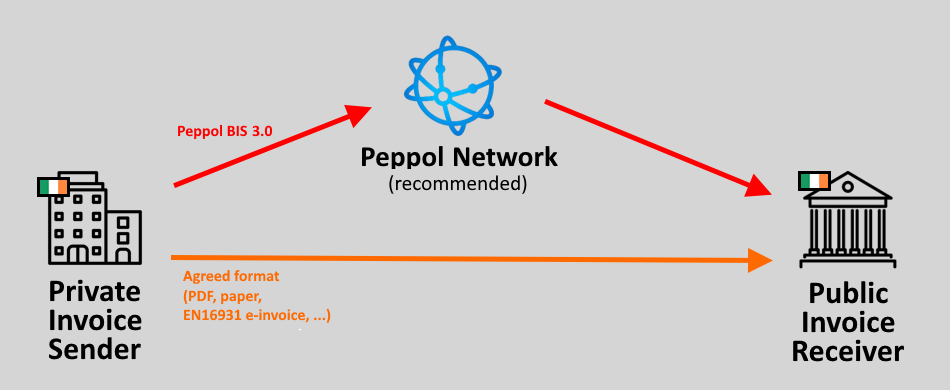
All Irish public administrations are able to receive and process electronic invoices compliant with the EN 16931 from their suppliers. The encouraged method is via the Peppol network in Peppol BIS 3.0 format.
B2B Transactions
Phased e-invoicing and real-time reporting mandate from 2028
E-invoicing is currently allowed, and will become mandatory in the coming years (2028-2030) in anticipation of the ViDA directive, likely through the Peppol network, and will include e-reporting to the tax authority.
B2C Transactions
No e-invoicing obligation
No e-invoicing or e-reporting obligation applies to business-to-consumer transactions in Ireland.
Ireland
Table of Contents
What the Law Says
B2G E-Invoicing
Since 2020, all public entities in Ireland have been able to receive and process electronic invoices compliant with the European Norm (EN) 16931.
However, the framework set out in Statutory Instrument 258/2019 [↗︎] does not require suppliers to public administrations to issue e-invoices. They may therefore still send PDF or paper invoices.
Where suppliers choose electronic invoicing, Ireland recommends the use of the Peppol network, with invoices exchanged in the Peppol BIS Billing 3.0 format, supplemented where relevant by Irish specifications (EI-CIUS).
Invoices must generally be archived for six years.
B2B E-Invoicing
Although there is currently no legal obligation to issue e-invoices, Ireland announced in October 2025 its intention to introduce electronic invoicing and reporting obligations in three phases, from late 2028 to late 2030.
Current legislation therefore still allows trading partners to exchange invoices through several methods, including:
- Paper invoices
- PDF invoices supported by an electronic signature or a complete audit trail
- Electronic invoices in any format, provided that both parties agree
The upcoming B2B e-invoicing mandate follows a public consultation [↗︎] and will be implemented as part of a VAT modernisation action plan [↗︎], in preparation for the ViDA directive.
The planned implementation timeline is as follows:
- November 2028: mandatory B2B e-invoice reception for all businesses, and mandatory issuance and e-reporting for large companies.
- November 2029: mandatory domestic B2B e-invoicing and e-reporting for businesses involved in EU cross-border B2B trade.
- July 2030: full ViDA compliance, with mandatory cross-border e-invoicing and e-reporting for intra-EU transactions.
The Irish Tax and Customs Authority (Revenue) has indicated that it has begun detailed analysis and technical preparations covering the required legislative changes, as well as the strategic, operational and IT-system requirements for successful implementation.
However, detailed legislation, public guidance and technical documentation of the future mandate are not yet available.
Invoices must generally be archived for six years.
B2C E-Invoicing
Ireland does not have a B2C e-invoicing or e-reporting mandate.
Companies may continue to issue business-to-consumer invoices and receipts through their usual channels, including paper invoices, PDF invoices sent by email and printed receipts.
Timeline
B2G e-invoicing mandatory in reception
All public administrations in Ireland must be able to receive and process electronic invoices compliant with the EN 16931 (but there is no issuance obligation for the suppliers)
B2B e-invoicing mandate phase 1
E-invoicing will become mandatory in reception for all companies, and in emission for large companies
B2B e-invoicing mandate phase 2
Domestic B2B e-invoicing will become mandatory for all businesses involved in trade with the EU.
B2B e-invoicing mandate phase 3
Full ViDA compliance: cross-border e-invoicing & e-reporting mandatory for all transactions with the EU
Latest E-Invoicing News in Ireland
European Commission calls for public input to shape the future of EU e-invoicing
EN 16931 update: the next step in e-invoicing is on its way
Technical Details (B2G)
Irish public entities must be able to receive electronic invoices compliant with the European Norm (EN) 16931. The Peppol network serves as the recommended national delivery approach, but suppliers are not required to issue e-invoices, and may still submit invoices in PDF or paper form.
Peppol as the recommended e-invoicing method
Ireland has selected the Peppol network as its national approach for transmitting B2G e-invoices. The Office of Government Procurement (OGP) acts as the Irish Peppol Authority, overseeing Ireland’s implementation of the network and supporting its use across the public sector.
Where Peppol is used, invoices are exchanged in the Peppol BIS Billing 3.0 format. Additional local requirements may apply depending on the receiving public entity, in the form of Irish specifications known as EI-CIUS.
Ireland does not operate a single central platform for all public entities. As Peppol is recommended rather than mandatory, not all Irish public administrations are reachable through the network.
Suppliers should therefore confirm the appropriate invoice transmission method with the relevant public body before sending an invoice, or they can use the Peppol Online Directory [↗︎] to verify that the recipient is reachable through the network and to retrieve its Peppol identifier. They must also include any routing reference and other fields required by the recipient.
The Irish eInvoice Guideline for Shared Services [↗︎] sets out common requirements for suppliers invoicing central government, local authorities, health-sector bodies and education-sector bodies.
Other permitted delivery methods
Suppliers are not required to issue electronic invoices to Irish public entities. They may therefore continue to submit invoices in PDF or paper form.
A supplier may also send a structured e-invoice compliant with the European Norm (EN) 16931, as Irish public entities are required to be able to receive and process such invoices.
Depending on the public entity, the electronic invoice may be sent through a wide range of delivery methods, including Peppol, email or direct one-to-one EDI connections.
In every case, the supplier and public recipient must first agree on the applicable delivery method and any recipient-specific requirements.
Technical Details (Upcoming B2B Mandate)
E-invoicing is not currently mandatory in Ireland, but a phased framework is scheduled to begin in November 2028. It is expected to rely on the Peppol network and will progressively extend to more businesses, transaction types and reporting obligations.
Mandate guidance
The VAT Modernisation action plan [↗︎], published in October 2025 and further updated in July 2026, provides some initial guidance regarding the upcoming mandate. While it does not yet set out detailed technical specifications, it confirms that Ireland’s B2B e-invoicing framework is being developed with the implementation of the ViDA directive in mind.
The framework also reflects recommendations from stakeholders set out in the report on the initial public consultation [↗︎], published in June 2024. These include aligning digital reporting with EN 16931.
This public consultation also outlined, as a suggestion, that to ensure a successful e-invoicing implementation, “unnecessary strict definitions or the exclusive adoption of particular standards or technologies, particularly with regards to B2B relationships”, shouldn’t be adopted. But at the same time, it noted that the “the technical structure of e-invoices required for domestic transactions should be consistent with those required for crossborder transactions under ViDA”.
Revenue has indicated that detailed guidance and technical specifications will be published well in advance of each implementation phase.
Expected e-invoice format & delivery
Ireland’s existing B2G framework relies on the Peppol network, and the Irish Tax and Customs Authority (Revenue) is working with the Office of Government Procurement to prepare the B2B reform.
Irish authorities are therefore expected to leverage the Peppol network, although Revenue has not yet formally confirmed that its use will be mandatory or exclusive. If this approach is confirmed, Ireland could implement the Peppol BIS / PINT-EU format through its next 4.0 release, taking account of the latest EN 16931 developments.
Additional formats could also be accepted, provided that they comply with the European standard and meet any applicable conditions.
Likewise, alternative e-invoice delivery methods outside the Peppol network may be permitted, notably by building on “various existing technical infrastructures”.
The Invoicing Hub Word
Ireland
Like many Northern European countries, Ireland has implemented Directive 2014/55/EU, which requires EU Member States to support B2G electronic invoicing. More specifically, Ireland adopted the least restrictive approach by requiring public entities to be capable of receiving electronic invoices compliant with EN 16931, without imposing an obligation on suppliers to issue e-invoices.
With the upcoming implementation of the ViDA directive, expected by 2030, Ireland is now actively preparing the introduction of a B2B e-invoicing mandate, following a path similar to that of the UK and the Netherlands.
This future framework is expected to rely heavily on the Peppol network and to be introduced progressively from the end of 2028 onward.
Ireland’s approach appears pragmatic and carefully structured. By leveraging Peppol, the country should be well positioned to ensure compliance with ViDA requirements while also facilitating both domestic and cross-border trade for Irish businesses. This model is expected to deliver benefits for both companies and public authorities.
Get your Project Implemented
Gold Sponsor
Silver Sponsors
Official Resources [↗︎]
Homepage of the Irish Tax & Customs Authority
Irish Peppol Authority
Collection of useful information provided by the Office of Government Procurement
Initial guidance on the upcoming B2B e-invoicing mandate
Entire set of official Peppol BIS 3.0 specifications
Official directory of worldwide Peppol-ready businesses
Related Resources
Latest News
Peppol & GENA e-invoicing conferences in Singapore – 17-19 November 2026
Spain’s B2B e-invoicing mandate will start in October 2027
Greece slightly postpones the next phases of its mandates
Slovakia proposes latest adjustments and an extended grace period
VeR expands the conversation around B2B e-invoicing
📩 Newsletter
Receive the latest e-invoicing news, directly in your mailbox, once a month.