E-Invoicing in Spain:
2027-2028 Mandate, SPFE & FACe
Last update: 2026, November 4
Summary
Spain will introduce mandatory B2B e-invoicing in 2027â2028 through the public SPFE platform and/or private exchange platforms. B2G e-invoicing has also been mandatory since 2015 in the country, mainly through FACe, although regional and local public entities may use different entry points.
B2G Transactions
Mandatory e-invoicing
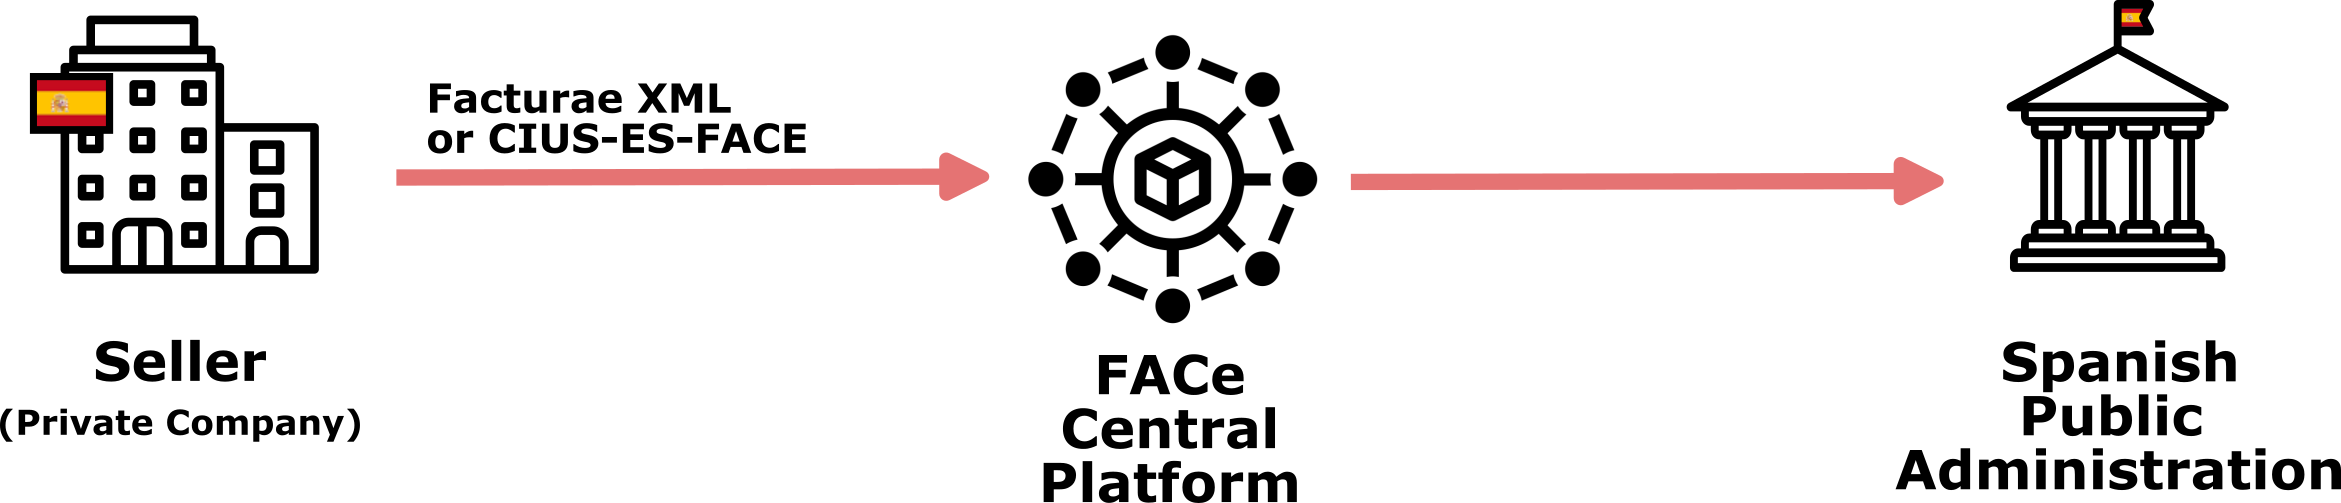
Suppliers must send electronic invoices to Spanish public administrations via the central platform âFACeâ in Facturae XML file format, although local public administrations and some regions such as the Basque Country may have specific requirements.
B2B Transactions
Mandatory phased e-invoicing from 2027-2028
E-invoicing will become mandatory for domestic transactions starting with large companies end 2027, through the SPFE central platform, private service providers, or a combination of both.
B2C Transactions
No e-invoicing obligation
No e-invoicing or e-reporting obligation applies to business-to-consumer transactions in Spain.
Other Obligations
Immediate Supply of Information (SII) & VERI*FACTU
Immediate Supply of Information (SII), already applicable: e-reporting mandatory for all transactions of mostly large companies (>6M⏠turnover).
VERI*FACTU, with likely implementation end 2028: use of compliant accounting software for all companies not in the scope of SII.
Spain
Table of Contents
What the Law Says
B2G E-Invoicing
B2G e-invoicing has been mandatory in Spain since 2015, and suppliers to public entities are required to transmit their invoices electronically.
To facilitate this process, a central platform called âFACeâ is available. Companies can exchange invoices in the standardised Facturae XML format, with a digital signature. FACe also accepts UBL and CII invoices that follow the CIUS-ES-FACE local specifications, which comply with the European Norm (EN) 16931.
Spain has a highly decentralised public administration, and FACe and the Facturae format are mandatory only for central government bodies. Other public administrations can use different entry points and may therefore be not reachable through FACe.
Invoices must generally be archived for six years.
B2B E-Invoicing
E-invoicing will become mandatory for B2B transactions in 2027-2028.
In September 2022, the âCrea y Creceâ law [âïž] (âCreate & Growâ) was published, laying the foundations for a future countrywide B2B e-invoicing obligation. The mandate was confirmed in October 2026 through Order HAC/1028/2026 [âïž].
The mandate will be implemented in three phases:
- October 6, 2027: mandatory B2B e-invoicing for large companies (annual turnover > âŹ8 million), with a readable PDF version of the invoice required during the first 12 months, and mandatory invoice statuses transmission
- October 6, 2028: mandatory B2B e-invoicing for SMEs and sole traders
- October 6, 2029: mandatory invoice statuses transmission for SMEs and sole traders
The obligation includes the issuance and exchange of B2B electronic invoices, invoice statuses (acceptance, rejection and payment), and e-reporting to the AEAT (the Spanish tax administration) through the SPFE central platform.
While the legal framework is now in place, detailed technical specifications for SPFEÂ are still expected to be published by the AEAT.
In the meantime, businesses can still transmit invoices in the following ways:
- Paper-based invoices
- PDF invoices with an e-signature or a complete audit trail
- EDI, upon mutual agreement
Invoices must generally be archived for six years.
Additional e-invoicing & e-reporting requirements
Most Spanish large businesses are subject to the SII obligation. Smaller businesses are instead subject to VERI*FACTU, or to TicketBAI in Basque Country.
The Immediate Supply of Information (SII) mandate consists of reporting tax information on all transactions to the tax authority within four business days. It mainly applies to large companies, but not only:
- Large companies with annual turnover above âŹ6 million
- Companies that are part of a VAT group
- Companies registered under REDEME (the Monthly Refund Registry)
Smaller companies outside the scope of the SII obligation have the option to adopt it voluntarily, or instead they will be subject to VERI*FACTU, theoretically starting from October 2028 following a several postponements [âïž].
Under this upcoming mandate, businesses will be required to use compliant accounting software (SIF, Sistema InformĂĄtico de FacturaciĂłn) that ensures invoice records cannot be tampered with and makes invoice data available to the AEAT.
In the Basque Country, VERI*FACTU requirements do not apply and businesses must instead comply with TicketBAI requirements, which also rely on compliant accounting software to prevent the tampering of invoices.
Timeline
B2G e-invoicing becomes mandatory
B2G e-invoicing is mandatory using the FACe central platform and the Facturae format.
Introduction of SII
Large companies (>6MâŹ) must report all transactions to the tax authority within 4 business days according to the "Immediate Supply of Information (SII)" mandate
Crea y Crece law
Publication of the law introducing a phased roll-out of mandatory B2B e-invoicing
B2B e-invoicing mandatory for large companies
The first phase of the B2B e-invoicing mandate will apply to large businesses (turnover > 8 MâŹ), including invoice statuses transmission
B2B e-invoicing mandatory for remaining companies
The second phase of the B2B e-invoicing mandate will apply to SMEs and sole traders, with no invoice statuses transmission at first
VERI*FACTU start date?
VERI*FACTU and the requirement to use compliant accounting software should start at this date, subject to official legislative confirmation
B2B e-invoicing mandatory invoice statuses
The third phase of the B2B e-invoicing mandate will apply to SMEs and sole traders, requiring them to exchange invoice statuses
Latest E-Invoicing News in Spain
New details on Spain’s upcoming B2B e-invoicing obligation
Spanish B2B e-invoicing technical guidance published
Technical Details (B2G)
Suppliers to Spanish public administrations must submit their invoices electronically, generally through the FACe central platform.
Invoice content & format
B2G e-invoices submitted through FACe must be issued in the Facturae format, Spainâs XML-based e-invoice format.
FACe also supports UBL and CII invoices compliant with CIUS-ES-FACE, a local specification that applies the European Norm (EN) 16931 to the platformâs requirements. However, this option remains rarely used in practice.
Additionally, e-invoices submitted to FACe must be digitally signed using a XAdES signature.
Finally, each invoice must be properly addressed to the relevant public entity, i.e. the invoice recipient, by specifying its DIR3 codes. These can be found in the DIRe online directory [âïž] and consist of three unique identifiers maintained by the Common Directory of Organisational Units and Offices:
- The identifier of the Oficina Contable (Accounting Office)
- The identifier of the Ărgano Gestor (Managing Office)
- The identifier of the Unidad Tramitadora (Processing Unit)
Small suppliers without an e-invoicing solution can use the free MiFacturae web application [âïž] to manually create, validate and sign their Facturae invoices before submitting them to FACe.
Invoice delivery
Spanish authorities have adopted a centralised exchange model. In all Spanish regions except the Basque Country, private businesses must submit their B2G e-invoices through the FACe central platform (Punto General de Entrada de Facturas ElectrĂłnica).
However, FACe is mandatory for central government entities but optional for regional and local administrations. As a result, some public entities may not be directly reachable through FACe.
In such cases, the invoice sender, i.e. the supplier to the public administration, should contact the relevant public entity directly to confirm the appropriate delivery method. In some cases, the supplier may need to address the invoice to the AdministraciĂłn General del Estado (the regionâs central administration) and provide the DIR3 code of the targeted local administration.
Technical Details (2027-2028 B2B Mandate)
B2B e-invoicing will become mandatory in 2027-2028 through the SPFE central platform and/or private service providers.
Invoice delivery
The AEAT (Spainâs tax authority) has designed what is primarily a centralised exchange model, relying on the free SPFE central platform. Businesses can send and receive their electronic invoices through the platform, which will automatically extract the tax data relevant to the AEAT.
Smaller businesses will be able to use a free web application on the AEAT electronic portal for individual invoice issuance, invoice-status reporting, consultation and download.
Detailed technical specifications for SPFE web-service integration, including access conditions and volume limits, are still expected to be published by the AEAT.
Alternatively, businesses can rely on Private Exchange Platforms (PPI, Plataformas Privadas de Intercambio), which are responsible for establishing direct one-to-one connections with other PPIs to enable direct invoice exchanges between businesses. In this case, the senderâs PPI must transmit a copy of the invoice in UBL 2.5 format to the SPFE so that the AEAT can access the relevant tax data.
In addition to using either the SPFE or PPIs exclusively, businesses may also use a combination of PPIs and the SPFE, for example:
- Invoice sender â Sending PPI â SPFE â Invoice receiver
- Invoice sender â SPFE â Receiving PPI â Invoice receiver
- Invoice sender â Sending PPI â SPFE â Receiving PPI â Invoice receiver
PPIs do not require formal certification or prior approval from the authorities, so no central official list is currently available. However, they must meet a comprehensive set of operational, security and interoperability requirements set out in Royal Decree 238/2026 [âïž].
Invoice format
For all invoices exchanged through the SPFE, companies and PPIs are required to use the UBL 2.5 XML format, which complies with the European Norm (EN) 16931 and serves as the mandateâs standard format.
When a direct one-to-one connection is used between two PPIs, other invoice formats are also permitted, provided that the senderâs PPI also transmits a UBL copy of the invoice to the SPFE:
- CII (XML, compliant with the EN 16931)
- Facturae (XML, Spainâs B2G e-invoicing format)
- EDIFACT
The inclusion of these formats, particularly EDIFACT, which is widely used across several industries, should allow businesses already using EDI systems to continue operating with minimal adjustments.
During the first 12 months of the mandate, large suppliers must also provide a readable PDF version of the electronic invoice, as their smaller customers will not yet be legally required to receive and process e-invoices until October 6, 2028.
Invoice statuses
The B2B mandate requires invoice recipients to provide updates to the invoice issuer through invoice response messages at two key stages of the invoice lifecycle:
- Commercial acceptance or rejection of the invoice, with corresponding date
- Full payment of the invoice, with corresponding date
Recipients must also report the invoiceâs full payment or rejection to the SPFEÂ in UBL ApplicationResponse format. This information is made available to the AEAT and supports the monitoring of payment terms and late payments.
Additional Requirements
SII e-reporting for (mostly) large businesses
Businesses in scope of the Immediate Supply of Information (SII â Suministro Inmediato de InformaciĂłn) need to report the required invoice-record data to the AEAT, which will use it to build the relevant VAT registers almost in real time. These include the registers for issued invoices, received invoices, capital goods and certain intra-EU transactions.
For regular or high-volume reporting, businesses submit these records through web services using the AEATâs proprietary XML messages. The service requires an accepted electronic certificate and can be used by the taxpayer, an authorised representative or a registered intermediary. Each submission may contain up to 10,000 invoice records.
Businesses with lower volumes, or those needing to report isolated invoice records, can instead use the online SII form on the AEAT portal [âïž].Â
The AEAT provides detailed SII technical documentation [âïž], including XML schemas, web-service WSDL files, validation rules, error codes and an external testing environment.
Smaller companies: VERI*FACTU
Businesses in scope of VERI*FACTU must use a compliant invoicing system, known as a SIF (Sistema InformĂĄtico de FacturaciĂłn).Â
A SIF must produce standardised invoice records and ensure their integrity, traceability, preservation and inalterability.Â
Invoices issued through a SIF must include a QR code, allowing the recipient to access key invoice details.
The AEAT provides official VERI*FACTU guidance and technical documentation [âïž].
Basque Country: Ticket BAI
TicketBAI is a regional invoicing and tax-reporting framework used in the Basque Country, requiring businesses within scope to use a TicketBAI-compliant invoicing solution when issuing invoices or sales receipts.
The three provincial tax authorities, in Ălava, Gipuzkoa and Bizkaia, operate their own TicketBAI services and have introduced the requirements according to their own timetables.
For each invoice or receipt, the invoicing solution must:
- generate a TicketBAI XML reporting file
- apply an XAdES electronic signature
- include information from the preceding invoice in the sequence, creating a chaining mechanism designed to make subsequent alteration or deletion detectable
- include a unique TicketBAI identifier or a QR code on the invoice, allowing the recipient to verify the invoice record with the relevant provincial tax authority
- submit the XML file to the relevant provincial tax authority, generally immediately after the invoice is issued
The invoice delivery is not regulated by the mandate, and businesses may therefore use their usual methods, including paper or PDF.
Each provincial tax authority publishes its own technical documentation, including the XML schemas, signature rules and submission services:
The Invoicing Hub Word
Spain
Spain has developed a complex e-invoicing landscape over time.
For B2G transactions, the FACe central platform covers most situations, but not every local public entity is reachable through it.
The Basque Country also applies its own TicketBAI framework, with separate implementation requirements in each of its three provinces.
The upcoming B2B e-invoicing mandate combines a centralised exchange model through the SPFE central platform, which does not follow the decentralised approach anticipated under ViDA, with Private Exchange Platforms (PPIs) that will exchange invoices through traditional one-to-one EDI connections.
Spanish authorities also impose additional invoice-data requirements through the SII and VERI*FACTU frameworks.
Together, these requirements place a considerable burden on businesses, which must navigate overlapping invoicing, software and tax-reporting obligations with different formats, data requirements, deadlines and reporting frequencies.
Get your Project Implemented
Gold Sponsor
With PA registration in France and readiness for Spainâs mandate, we support decentralized and reporting models with audit-ready status flows.
Our SaaS platform integrates natively with SAP ECC/S/4HANA and connects to other ERPs, orchestrating formats like UBL, CII, Factur-X and Facturae across 35+ countries.
Backed by 40 years of integration expertise, we turn evolving mandates into streamlined, data-first operations, improving control, speed, and cost from receipt to payment.
Silver Sponsors
Official Resources [âïž]
Tax authority, supervising the e-invoicing mandates in Spain
Official guidelines & resources on the upcoming B2B e-invoicing mandate
Spain B2G central platform
Technical specifications of the Facturae B2G format
Technical specifications of the Veri*Factu requirements and the SIF (accounting software)
Technical specifications of the SII (Immediate Supply of Information) law requirements
Official directory used to identify public recipients and their DIR3 codes
Related Resources
Advertisement
Latest News
India expands e-invoicing requirements from January 2027
Denmark clarifies and introduces new digital accounting requirements
UK publishes the roadmap to its 2029 e-invoicing mandate
A busy October ahead of Slovakiaâs 2027 e-invoicing mandate
UAE authorities release minor electronic invoicing amendments
đ© â Newsletter
Receive the latest e-invoicing news, directly in your mailbox, once a month.