E-Invoicing in Poland:
B2G & B2B mandate via KSeF
Last update: 2026, October 20
Summary
Poland is implementing an e-invoicing mandate for B2G and B2B transactions through the KSeF central platform. It already applies to most businesses nationwide and will extend to the remaining very small businesses at the beginning of 2027.
B2G Transactions
Partially mandatory e-invoicing
B2G e-invoicing was already possible through the PEF central platform and is now mandatory for most businesses, with KSeF available as another option.
Very small businesses not yet covered by the mandate will come into scope in 2027.
B2B Transactions
Partially mandatory e-invoicing
B2C Transactions
No e-invoicing obligation
No e-invoicing or e-reporting obligation applies to business-to-consumer transactions in Poland.
Poland
Table of Contents
What the Law Says
B2G E-Invoicing
Suppliers must send electronic invoices to Polish public administrations, except for very small businesses, which will be required to do so from 2027.
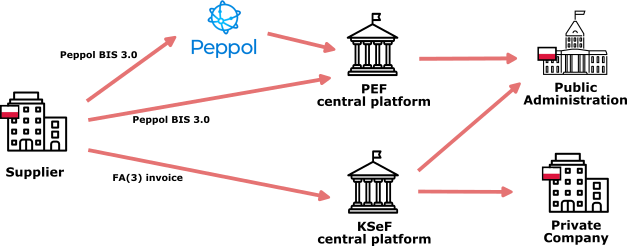
Public entities have been able to receive electronic invoices since 2019 under the Act of November 9, 2018 on electronic invoicing in public procurement [↗︎]. Invoices could be transmitted through the PEF central platform, in Peppol BIS 3.0 format or the “Faktura specjalizowana” variant, either directly or via the Peppol network.
Following several delays, suppliers became required to send B2G invoices electronically in 2026. The mandate is being implemented in three phases under the Act of August 5, 2025 amending the VAT Act [↗︎]:
- February 1, 2026: B2G e-invoicing mandatory for large businesses, with sales exceeding PLN 200 million (~ 45 M€)
- April 1, 2026: B2G e-invoicing mandatory for medium & small businesses
- January 1, 2027: B2G e-invoicing mandatory for remaining very small businesses, with monthly invoiced sales of up to PLN 10,000 including VAT (~ 2,300 €)
The 2026–2027 mandate relies on the KSeF central platform, through which suppliers can submit invoices in the FA(3) XML format. Suppliers can also continue to use the PEF platform to submit their B2G invoices.
A limited number of exceptions [↗︎] apply. For example, the mandate does not cover foreign suppliers without a business establishment in Poland or certain documents recognised as invoices, such as transport tickets and insurance policies.
Additionally, a grace period applies until December 31, 2027, where no sanctions will be issued, allowing more time to companies to fully comply with the mandate.
Invoices must generally be archived for five years. Invoices issued through KSeF are automatically stored on the platform for ten years [↗︎].
B2B E-Invoicing
B2B e-invoicing is becoming mandatory in Poland in 2026–2027.
The e-invoicing mandate is overseen by the Ministry of Finance, Poland’s tax authority, and covers both B2G and B2B transactions. It is being implemented in three phases under the Act of August 5, 2025 amending the VAT Act [↗︎], with the following requirements for B2B transactions:
- February 1, 2026:
- Reception of B2B e-invoices becomes mandatory for all businesses in scope.
- Issuance of B2B e-invoices becomes mandatory for large businesses, with sales exceeding PLN 200 million (~ 45 M€).
- April 1, 2026: issuance of B2B e-invoices becomes mandatory for medium and small businesses.
- January 1, 2027: issuance of B2B e-invoices becomes mandatory for the remaining very small businesses, with monthly invoiced sales of up to PLN 10,000 including VAT (~ 2,300 €).
B2B invoices must be sent in the FA(3) XML format through the new KSeF central platform. Other formats and transmission methods cannot be used to fulfil this obligation, and the PEF platform cannot be used for B2B transactions.
The same exceptions [↗︎] apply as for B2G transactions. The government has also announced extending the grace period for KSeF penalties until December 31, 2027.
Invoices must generally be archived for five years. Invoices issued through KSeF are automatically stored on the platform for ten years [↗︎].
B2C E-Invoicing
Poland does not have a B2C e-invoicing or e-reporting mandate.
Companies may continue to issue business-to-consumer invoices and receipts through their usual channels, including paper invoices, PDF invoices sent by email and printed receipts.
They may also voluntarily issue B2C invoices through the KSeF central platform, with the final consumer able to retrieve them through a link or a QR code.
Timeline
B2G E-Invoicing - Mandatory Acceptance
All Polish public administrations must accept e-invoices through the "PEF" platform in PEPPOL BIS 3.0 and the extended "Faktura specjalizowana" format.
B2G & B2B E-Invoicing Mandate - Phase 1
All companies must be able to receive electronic invoices, and large companies (PLN > 200M) must send electronic invoices
B2G & B2B E-Invoicing Mandate - Phase 2
All companies (excluding micro-businesses) must issue electronic invoices via KSeF countrywide
B2G & B2B E-Invoicing Mandate - Phase 3
E-invoicing through KSeF platform mandatory for all companies, including micro-businesses
End of the mandate grace period
No penalties will be issued to companies not perfectly complying with the e-invoicing mandate until this date.
Latest E-Invoicing News in Poland
European Commission calls for public input to shape the future of EU e-invoicing
Poland’s KSeF phase 2 takes effect after solving initial hurdles
Technical Details - PEF platform (B2G only)
The PEF central platform was launched in 2019, enabling Polish public administrations to receive electronic invoices from their suppliers. As B2G and B2B e-invoicing becomes mandatory nationwide in 2026-2027, PEF remains an option for suppliers sending e-invoices to public customers.
Central platform & connectivity
Since 2019, businesses have been able to send electronic invoices to public administrations through the PEF platform [↗︎] (Platforma Elektronicznego Fakturowania).
Suppliers of Polish public administrations can connect their invoicing systems to PEF through an API [↗︎]. The platform is also connected to the Peppol network, facilitating interoperability, particularly for cross-border invoices.
Alternatively, smaller companies without API or Peppol capabilities can use PEF’s free online tools to create and submit their B2G invoices manually.
Unlike KSeF, the PEF platform also supports the exchange of other documents, such as delivery advice, acknowledgements of receipt and accounting notes.
Since February 2026, suppliers sending invoices to public customers can also use the KSeF platform, as described below.
Invoice format
Invoices sent to PEF through the Peppol network can use the Peppol BIS Billing 3.0 format [↗︎].
In case of suppliers submitting their B2G e-invoices directly via API, PEF also supports “Faktura specjalizowana” [↗︎], a specialised UBL format based on an extension of Peppol BIS 3.0. The Faktura specjalizowana format adds fields for specific Polish invoicing needs, such as utility statements, additional gross data or invoice factoring.
Polish public administrations can receive invoices through PEF in these formats, both compliant with the European Norm (EN) 16931.
Technical Details - KSeF Platform (B2G + B2B)
The 2026-2027 e-invoicing mandate applies to both B2G & B2B transactions, and revolves around the new KSeF central platform. All Polish invoice receivers (whether private businesses or public entities) are reachable through KSeF.
Central platform & format
Electronic invoicing is becoming mandatory for B2G and B2B transactions through a new platform called KSeF [↗︎] (Krajowy System e-Faktur), although the existing PEF central platform also remains available for B2G transactions.
The platform uses a dedicated Polish invoice format known as FA(3) [↗︎]. This format is XML-based and, although it follows the semantic data model and principles of the European Norm (EN) 16931, it is unfortunately not compliant with the standard, limiting wider interoperability.
Connection to the KSeF platform is possible via API [↗︎]. Additionally, free tools [↗︎] are available to help small businesses comply with the mandate, including the option to submit invoices manually through direct input on the platform.
The KSeF platform serves both invoice issuers, who use it to send their invoices, and recipients, who use it to receive them. For every invoice it validates, KSeF assigns an official invoice number [↗︎], which functions as a unique invoice identifier.
This setup follows a Centralized Exchange model, similar to the system already in place in Italy.
Invoice attachments
Invoice attachments are supported by the KSeF platform [↗︎] and can be transmitted with the e-invoice. However, mandatory invoice data must be included directly in the XML. Attachments allow suppliers to share additional business information with their customers.
Companies wishing to issue and transmit invoices with attachments must first submit a notification through the e-Tax Office.
International transactions
For cross-border transactions, Polish sellers within scope must generally issue the invoice through KSeF, as they do for domestic B2B transactions.
However, when the customer is established abroad, the seller must also deliver the invoice to the buyer in an agreed format [↗︎], such as paper, PDF or an electronic format.
KSeF offline mode
In principle, suppliers issue invoices directly through KSeF in real time, a process known as online mode.
However, suppliers can also issue invoices outside KSeF using one of the offline modes [↗︎]. These modes can be used in situations such as system outages or scheduled maintenance.
Invoices issued offline must subsequently be submitted to KSeF to obtain an official KSeF number. The deadline depends on the situation:
- Offline24: no later than the business day following the invoice’s issuance.
- Scheduled unavailability: no later than the business day following the end of the unavailability.
- An officially announced KSeF outage: within seven business days after the outage ends.
When an offline invoice is delivered outside KSeF before it has been submitted to the platform, it must include two QR codes: an “OFFLINE” code, which allows the recipient to verify the invoice once it has been uploaded, and a “CERTYFIKAT” code, which helps verify the issuer’s identity.
QR verification codes
When a KSeF invoice is provided to a customer outside the platform, for example as a PDF or a printed document, it must include a QR verification code [↗︎]. This may apply to invoices sent to foreign customers or to consumers.
The QR code allows the recipient to check whether the invoice is available in KSeF and verify its details. Additional information is required to download the complete invoice.
For invoices issued offline and delivered outside KSeF before they have been submitted to the platform, two QR codes are required: one to verify the invoice once it has been submitted, and another to verify the issuer’s identity. These cases are described in the next section.
Additional benefits
In addition to the usual benefits of e-invoicing, such as automation and improved efficiency, the Polish tax authorities highlight several advantages of using KSeF:
- Invoice archiving: invoices issued through KSeF are archived on the platform for ten years [↗︎], generally removing the need for businesses to archive them separately during that period.
- Simplified reporting: businesses no longer need to provide a JPK_FA file for invoices held in KSeF [↗︎] when requested by the tax authorities.
- Faster VAT refunds: the standard VAT refund period has been reduced from 60 to 40 days [↗︎] for tax periods beginning from February 2026.
The Invoicing Hub Word
Poland
Poland has long faced significant VAT gaps, and mandatory e-invoicing is now being implemented nationwide to help address this issue.
The chosen model, based on one central platform, KSeF (or two if the existing PEF platform for B2G transactions is included), and one standard format, FA(3), makes e-invoicing relatively straightforward to implement for Polish companies. However, the language barrier can be challenging for multinational companies and service providers wishing to offer e-invoicing services in Poland.
The changing implementation timeline has added pressure on affected businesses, but the rollout of the mandate is now well underway. Meanwhile, the KSeF platform has undergone several improvements following extensive public consultations, which proved highly valuable.
However, the fact that the FA(3) format does not fully comply with the European Norm (EN) 16931, and that the centralised exchange model does not comply with the ViDA directive, raises questions. These choices may lead to additional work and costs for companies to remain compliant with European e-invoicing requirements.
Get your Project Implemented
Gold Sponsor
The API ensures invoices are validated, transmitted, and reported in line with local regulations. Supporting both real-time and post-audit models, it adapts to evolving legal requirements without heavy internal development.
Secure, scalable, and easy to integrate with ERP and accounting systems, A-Cube automates workflows, reduces compliance risk with transparency.
Silver Sponsors
Official Resources [↗︎]
Public entity supervising the e-invoicing mandate in Poland
Homepage of the KSeF central platform
Official guidelines & resources on the use of the KSeF central platform
Explanations about the main topics of the B2B mandate
Directory of technical specifications to connect to the KSeF central platform
Technical specifications of the Polish FA(3) format to be used on the KSeF central platform
Homepage of the PEF platform used for B2G transactions in Poland
Related Resources about Poland
Advertisement
Latest News
A busy October ahead of Slovakia’s 2027 e-invoicing mandate
UAE authorities release minor electronic invoicing amendments
New accreditation requirements for e-invoicing solutions in the Philippines
BMF publishes additional guidance on mandatory German e-invoicing
Peppol & GENA e-invoicing conferences in Singapore – 17-19 November 2026
📩 Newsletter
Receive the latest e-invoicing news, directly in your mailbox, once a month.