Skip to content

Advertisement

Become a gold sponsor - stacked
Contact us to learn about our sponsorship plans

E-Invoicing in Malaysia:
Clearance Mandate & MyInvois

Last update: 2026, October 14

Summary

Malaysia requires invoices to be issued electronically countrywide following a Clearance model. Electronic invoices must be validated through the MyInvois central platform before they can be delivered to their recipients.

B2G & B2B & B2C Transactions

Mandatory e-invoicing

All invoices in scope must be submitted to MyInvois for clearance in a proprietary UBL XML or JSON format. Once validated, the supplier must send to the recipient either the electronic invoice, or a readable PDF or paper version containing a QR code.

Malaysia

Table of Contents

What the Law Says

B2G & B2B & B2C E-Invoicing

Malaysia has gradually implemented a clearance e-invoicing mandate that applies to all types of transactions: B2G, B2B and B2C.

The mandate, overseen by the IRBM, Malaysia’s tax authority, was introduced in several phases based on annual turnover or revenue, starting on August 1, 2024, under the Income Tax (Issuance of Electronic Invoice) Rules 2024, P.U. (A) 265 [↗︎].

Since January 1, 2026, it has applied nationwide to all companies with annual turnover or revenue of RM 3 million or more (~€650K).

Suppliers must submit in-scope invoices to the MyInvois central platform in a proprietary UBL 2.1 format, available in XML or JSON. Once the invoice content has been verified, MyInvois validates it, assigns a Unique Identifier Number (UIN) and also provides the details required for the supplier to generate a QR code.

The supplier is then responsible for delivering the invoice to the buyer using a method agreed between the parties, typically as a PDF or paper document. The Malaysian Government nevertheless recommends electronic delivery via the Peppol network.

For B2C transactions at points of sale, many POS solutions can generate receipts containing a QR code that allows buyers to request an e-invoice after the transaction.

For small businesses not impacted by the e-invoicing mandate, e-invoicing via the MyInvois central platform remains possible under the same rules, while traditional methods also remain permitted:

  • Paper-based invoices
  • PDF invoices
  • Electronic invoices, exchanged for example via EDI or Peppol

Invoices must generally be archived for seven years. Cleared e-invoices remain also accessible through the MyInvois platform for the first two years.

Grace Period & Exemptions

Each taxpayer group in the rollout was initially granted a six-month grace period. 

For the final group within scope, the grace period [↗︎] runs longer, until December 31, 2027. It applies to companies with annual turnover or revenue between RM 3 million and RM 5 million (~€650K to ~€1.1M), which became subject to the mandate from January 1, 2026.

During this time, they are allowed to issue consolidated e-invoices monthly rather than a separate e-invoice for each transaction.

This grace period is supplemented by the e-Invoice Special Voluntary Disclosure Programme (SVDP) [↗︎], an amnesty programme also running until December 31, 2027. It allows taxpayers of any size to voluntarily regularise past or missing e-invoice submissions without penalties.

In addition, the official guidelines [↗︎] provide exemptions for certain entities, including much of the public sector, as the Government and State Governments fall outside the scope of the mandate.

Finally, businesses with annual turnover or revenue of less than RM3 million (~€650K) are exempt from mandatory e-invoicing, as confirmed by the official implementation timeline [↗︎] and the official FAQ [↗︎].

Timeline

E-Invoicing Mandatory - Large Companies

Large companies (turnover > RM 100 million) must send electronic invoices through the MyInvois central platform

E-Invoicing Mandatory - Mid-size Companies

The e-invoicing mandate starts applying to medium-sized companies (turnover > RM 25 million)

E-Invoicing Mandatory - Small Companies

The e-invoicing mandate starts applying to small companies (turnover > RM 5 million)

E-Invoicing Mandatory - Most Companies

All invoicing transactions must be performed in an electronic way through the MyInvois central platform, except for very small companies (turnover < RM 3 million) for which the mandate does not apply.

End of the grace period & amnesty period

End of the last grace period, for companies with annual turnover between RM 5 and 3 million, and of the e-invoice SVDP for all taxpayers.

Aug 1, 2024
Jan 1, 2025
July 1, 2025
January 1, 2026
December 31, 2027

Latest E-Invoicing News in Malaysia

Panoramic view of the Sultan Abdul Samad Building and Jalan Raja in Kuala Lumpur, Malaysia, showcasing the city’s iconic urban landscape.

Malaysia enables an e-invoice amnesty mechanism until end 2027

Malaysia introduces the e-invoice amnesty "SVDP" alongside updated guidelines, offering taxpayers a voluntary regularisation process.

Night photo of the skyline of Kuala Lumpur, capital of Malaysia

New exemption threshold and grace period for Malaysian small enterprises

In response to multiple concerns raised, the Malaysian Government has announced two key measures to ease the transition for small enterprises.
Skyline of Kuala Lumpur, capital of Malaysia

Malaysia extends e-invoicing deadline for small businesses

Small businesses with a revenue below RM 500K get more time to transition to digital invoicing and adapt to the new requirements.

Technical Details (B2G & B2B & B2C)

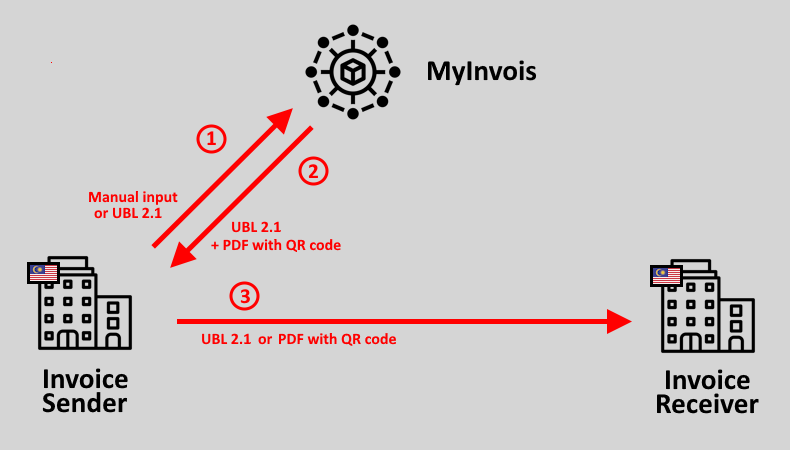
All invoices within the scope of Malaysia’s e-invoicing clearance mandate must be validated through the MyInvois central platform. The supplier is then responsible for delivery, most often in paper or PDF form, while the Government promotes Peppol for electronic exchange.

Schema of the Malaysia e-invoicing landscape using the MyInvois central platform for validation and delivery of the invoice by the supplier
Malaysia’s clearance model: invoice validation through MyInvois & invoice delivery by the supplier

MyInvois central platform

In Malaysia, all invoices within scope must undergo validation through the MyInvois central platform before they can reach their final recipient. 

The platform is operated by the Inland Revenue Board of Malaysia (IRBM), the country’s tax authority.

Suppliers can submit electronic invoices to MyInvois in two ways:

  • Manual data input through the MyInvois web interface [↗︎], which is suitable for low invoice volumes and companies without an automated e-invoicing solution.
  • Automated submission through the MyInvois REST API [↗︎], generally used by businesses or service providers integrating MyInvois into invoicing or ERP systems.

The official e-Invoice Guidelines [↗︎] and MyInvois Software Development Kit (SDK) [↗︎] provide detailed legal, operational and technical guidance.

Additionally, before using MyInvois, a business must access the platform through the MyTax portal [↗︎] and create or activate its taxpayer profile. The profile identifies the business and records key information, including its tax details, notification language and notification settings.

Invoice content & format

E-invoices submitted through the MyInvois API must use a proprietary format based on UBL 2.1, available in XML or JSON.

This format includes Malaysia-specific data requirements, code lists and validation rules defined by the IRBM. These are described in the MyInvois invoice structure documentation [↗︎] and validation rules [↗︎]. API-submitted invoices must also be digitally signed.

Among the mandatory fields, each e-invoice must include the relevant Tax Identification Number (TIN) used to identify the parties to the transaction.

Invoice validation

Once an e-invoice has been submitted, MyInvois checks that it complies with the applicable data and validation rules. If validation fails, the platform returns error messages so that the supplier can correct the invoice and submit it again.

If the validation succeeds, MyInvois assigns the e-invoice a Unique Identifier Number (UIN) and provides the data required for the supplier to generate a QR code, enabling later the buyer to verify the e-invoice’s validity and status through MyInvois.

The buyer is also notified through MyInvois that a validated e-invoice has been issued in its name and is available on the platform.

Invoice delivery

It is the supplier’s responsibility to ensure the invoice is delivered to the buyer. The supplier and the buyer are free to agree on their preferred delivery method.

In practice, many businesses will share a PDF invoice by e-mail. This visual representation must be generated by the supplier and include a QR code, created from the details previously provided by MyInvois upon clearance of the invoice.

Businesses may also exchange an electronic invoice. In this case, the electronic invoice must include the UIN assigned by MyInvois.

The UIN and QR code allow the buyer to verify that the invoice is valid and was properly cleared by the tax authority.

Following validation, a 72-hour window allows the supplier to cancel the invoice or the buyer to request its rejection.

E-invoice delivery via Peppol

The Malaysian government is promoting a national e-invoicing initiative through the Malaysia Digital Economy Corporation (MDEC), which has published official guidelines [↗︎]. 

This voluntary program relies on the Peppol network and encourages companies to adopt e-invoicing to leverage the numerous benefits of automation, such as faster processes and fewer manual errors.

Electronic invoices exchanged in Malaysia through Peppol must be formatted in the PINT-MY (Malaysian Peppol International) format [↗︎]. All Peppol requirements are further detailed in the Peppol Authority Specific Requirements [↗︎] for Malaysia.

Service providers wanting to offer Peppol services in Malaysia must be certified by the MDEC, which maintains lists of certified Peppol Service Providers [↗︎] and certified Peppol-Ready Service Providers [↗︎]. 

A Peppol solution provider may also handle the clearance part of the process by submitting the required UBL 2.1 data to MyInvois, retrieving the validation details and delivering the PINT-MY invoice to the recipient through Peppol.

Cross-Border Invoices

Cross-border invoicing requires the Malaysian party to report relevant transaction data to MyInvois. The invoice itself may however be exchanged with the foreign trading partner through any mutually agreed method.

Sending Cross-Border Invoices

Sending cross-border invoices does not differ significantly from domestic invoicing for a Malaysian company.

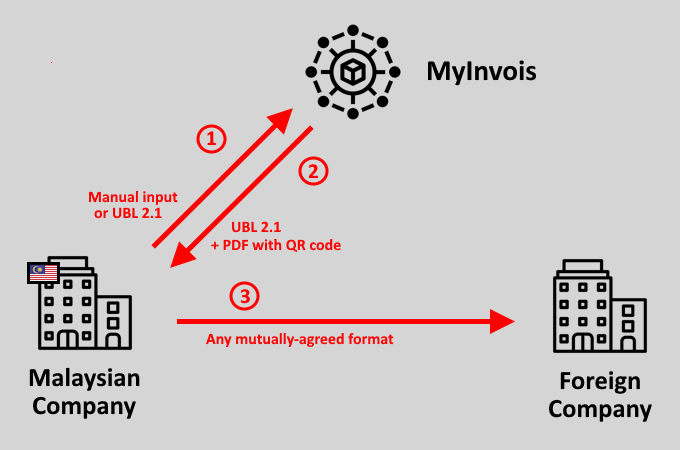
When a Malaysian seller invoices a foreign buyer, it must follow the mandated process by validating the e-invoice through MyInvois, then send a copy of the invoice to the foreign buyer in a mutually agreed format.

Schema of the management of the sending of cross-border invoices for an business operating in Malaysia
Click to enlarge

The only difference stands in the fact that Malaysian businesses are not required for foreign transactions to send to the buyer the UBL 2.1 e-invoice (with its UIN) or to include the QR code in the PDF or paper invoice. They can rather use any mutually agreed-upon format & channel with their foreign buyer.

Receiving Cross-Border Invoices

Receiving cross-border invoices introduces a bit more complexity for the Malaysian company.

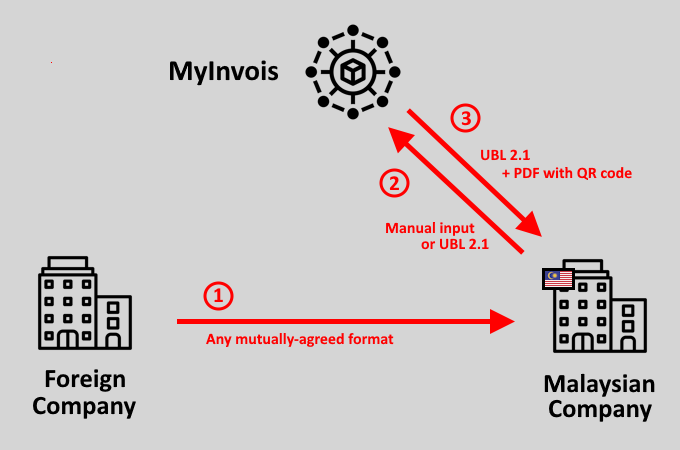
When a foreign seller invoices a Malaysian buyer, the foreign seller is free to issue the invoice as they see fit.

Then, the Malaysian buyer must subsequently issue a corresponding self-invoice and submit this self-invoice to MyInvois for validation.

Schema of the management of the reception of cross-border invoices for an business operating in Malaysia
Click to enlarge

The Invoicing Hub Word

Malaysia

Malaysia is adopting a e-invoicing clearance mandate akin to those in effect in Latin America. Under this approach, suppliers must submit invoice data to the MyInvois central platform for validation before delivering the invoice to the buyer. 

This model leaves trading partners free to use their existing delivery channels, including PDF or paper. It can therefore reduce the implementation scope for businesses, but it does not by itself ensure the structured, end-to-end exchange needed to unlock the full automation benefits of e-invoicing.

Nevertheless, Malaysia emerges as a pioneer in the Asia-Pacific region, and was among the first countries to implement a comprehensive e-invoicing mandate, setting a precedent for others to follow suit. 

Moreover, the Malaysia tax authority offers clear guidelines, detailed use cases, and comprehensive technical documentation, giving businesses and software providers a relatively clear basis for implementation.

Get your Project Implemented

Gold Sponsor

Become a gold sponsor - stacked
Contact us to learn about our sponsorship plans

Silver Sponsors

Contact us to learn about our sponsorship plans

Official Resources [↗︎]

Malaysia’s tax authority, in charge of the e-invoicing mandate in the country

Peppol Authority in Malaysia

Guidelines & technical specifications on the e-invoicing mandate, maintained by the IRBM

Collection of FAQs covering the mandate, sector-specific requirements and technical questions

MyInvois is part of the MyTax portal

Comprehensive set of technical resources to interact with the MyInvois platform

Guidelines, certified providers & technical specifications for the use of Peppol in Malaysia

Related Resources

Global mandates move fast. Get a quarterly, practical overview of e-invoicing updates, key deadlines, and what your team must act on.
A Comarch webinar analyzing France's e-invoicing mandate, covering the PPF/PA interoperability model and document lifecycle statuses.
Implement the E-Invoicing Reform for the Purchase Cycle. Download our guide to implementing e-invoicing for your purchasing processes.

Advertisement

Become a gold sponsor - stacked
Contact us to learn about our sponsorship plans

Latest News

Photo of the Merlion, a lion head fountain, in Marina Bay in front of the Singapore skyline

Peppol & GENA e-invoicing conferences in Singapore – 17-19 November 2026

Peppol Conference APAC 2026 takes place on 17-18 November, followed by the GENA IDT Summit on 19 November, both at the same venue in Singapore.

Spain’s B2B e-invoicing mandate will start in October 2027

Spain’s Ministerial Order is now published, triggering the countdown to mandatory B2B e-Invoicing and providing key technical rules

Greece slightly postpones the next phases of its mandates

Just one day before phase 2 of its e-invoicing mandate, Greece revised the implementation timetable for both e-invoicing and e-transportation.

Slovakia proposes latest adjustments and an extended grace period

A new bill outlines a six-month penalty-free period, removal of buyer-side e-reporting, alongside the release of valuable practical guidance.

VeR expands the conversation around B2B e-invoicing

VeR’s public events widen the discussion about B2B e‑invoicing as a driver for digitalization across the German economy
Chatbot icon at the colors of The Invoicing Hub

Try me 🙂

I’m an e-invoicing  expert and I might just surprise you!

📩 ‎ Newsletter

Receive the latest e-invoicing news, directly in your mailbox, once a month.